
Rebuilding Credit With a Used Car in Ontario: A Practical 12-Month Game Plan
Rebuilding Credit With a Used Car in Ontario: A Practical 12-Month Game Plan
Posted on September 28, 2026
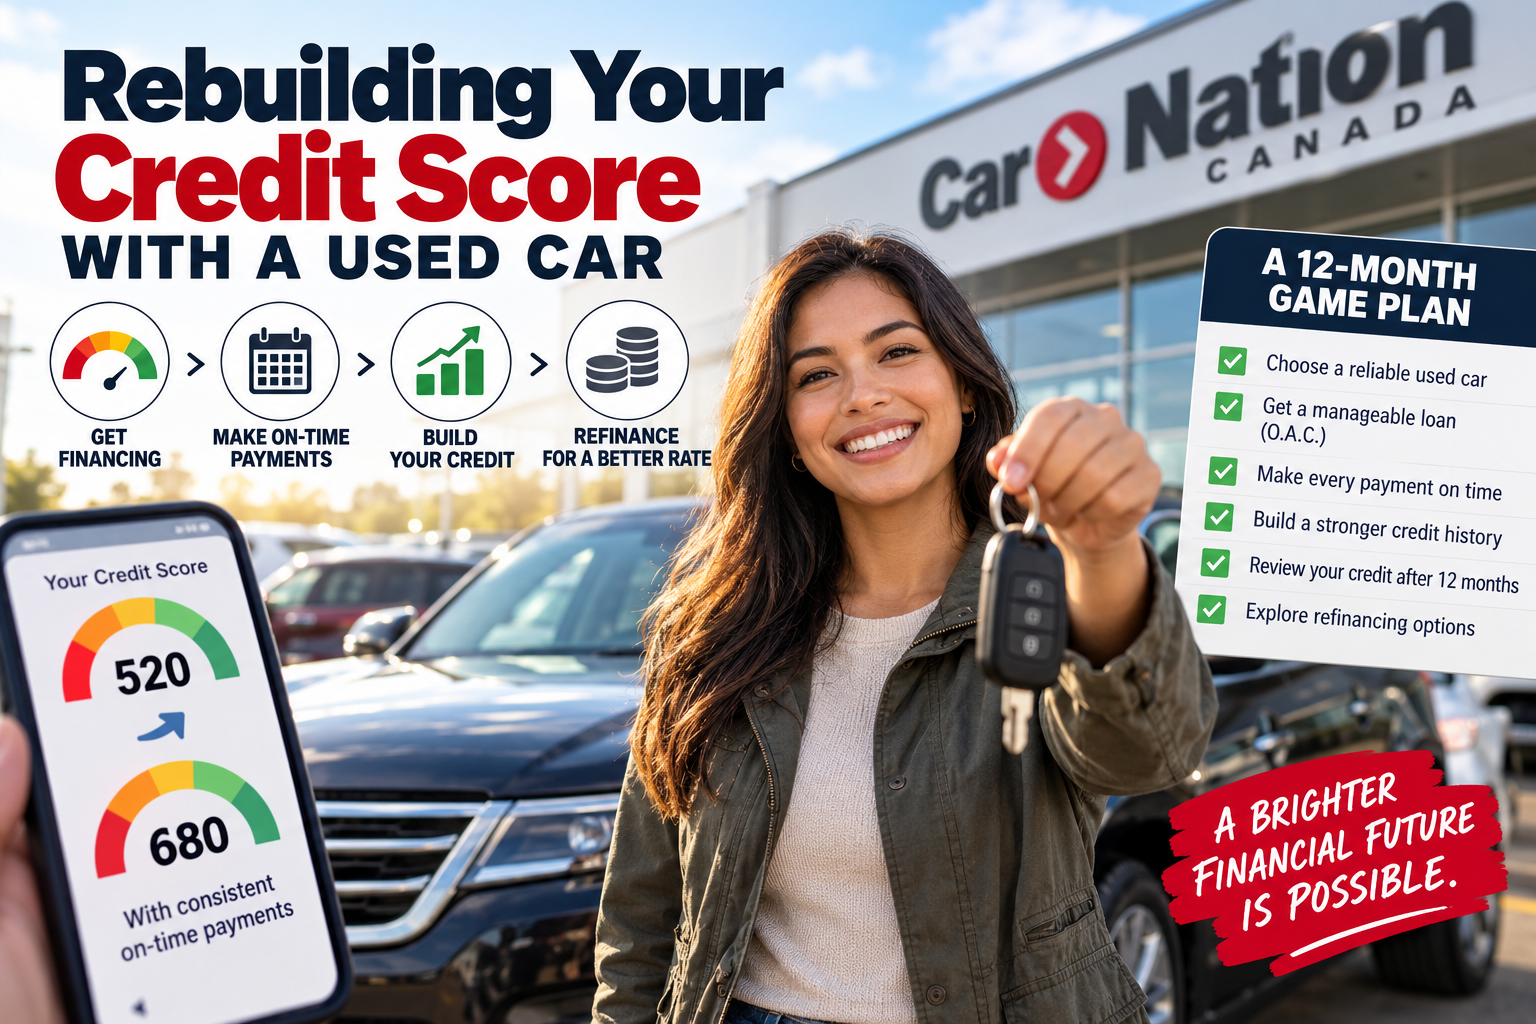
Rebuilding Credit With a Used Car in Ontario: A Practical 12-Month Game Plan
Rebuilding credit with a used car can work when the vehicle, payment, loan structure, and repayment plan all fit your real-world budget.
If your credit score has taken a hit after missed payments, a consumer proposal, bankruptcy, job disruption, divorce, unexpected expenses, or simply a difficult financial stretch, getting another vehicle can feel intimidating.
For Ontario drivers who genuinely need a car to get to work, take children to school, or handle everyday responsibilities, the objective should not be to borrow as much as a lender will approve. The better strategy is to find a dependable used vehicle with a payment you can consistently manage while using the next year to build a stronger credit history.
That is where rebuilding credit with a used car can become part of a larger financial comeback plan. Financing is never guaranteed, and a car loan by itself cannot guarantee that your credit score will increase. But responsible credit management and consistently paying obligations on time can contribute to a healthier credit history over time. TransUnion Canada specifically identifies punctual payments as an important part of improving credit health.
Key Takeaways
- A credit score in the 300–559 range may make borrowing more expensive, but your score is only one part of a lender's decision.
- Subprime auto financing can carry substantial interest costs. An APR such as 10.99% to 29.99% should be treated as an illustrative range, not a guaranteed rate tied to a particular score.
- Choose the vehicle based on your complete budget, not simply the maximum amount available through financing.
- Ask whether the lender reports your payment history to Canadian credit reporting agencies.
- Aim for every payment to arrive on time. Setting up automatic payments and maintaining a cash cushion can help.
- After roughly 12 months of responsible repayment, review your credit again and investigate whether refinancing or replacing the existing loan with a lower-cost loan makes financial sense.
- Refinancing is not automatic. You will have to qualify again, and the new loan should reduce your real borrowing cost after considering its rate, term, fees, and remaining balance.
- Financing options are available for many credit situations through our Car Nation Canada finance team. All financing is O.A.C. — On Approved Credit. Conditions may apply.
What Does a 300–559 Credit Score Mean for Used Car Financing?
Canadian credit decisions are more complicated than attaching one interest rate to one three-digit number.
TransUnion explains that there are multiple credit-scoring models, and creditors may use different scores and other information when evaluating an application. In general, stronger credit can help borrowers qualify for more favourable rates, while weaker credit may result in higher borrowing costs.
That means somebody with a score of 520 does not automatically receive the same rate as every other borrower with a 520 score.
A lender may also consider factors such as:
- Income and employment stability
- Existing monthly debt obligations
- How long you have lived at your address
- The vehicle being financed
- Amount being borrowed
- Down payment or trade-in
- Loan term
- Recent credit history
- Previous bankruptcies, proposals, collections, or missed payments
- The lender's own underwriting requirements
For borrowers rebuilding credit, double-digit interest rates are possible. You might see offers within a broad range such as 10.99% to 29.99% APR, but this is an example of what higher-cost borrowing can look like, not a promise, published rate schedule, or guaranteed range for people with a particular credit score.
The actual rate and terms available to you can only be determined after a lender reviews your application. Financing is O.A.C. Conditions may apply.
Why the Interest Rate Matters More Than Many Shoppers Realize
When your credit is bruised, it can be tempting to focus exclusively on one question:
"Can I afford the payment?"
That matters, but it is only half of the equation.
The Financial Consumer Agency of Canada advises vehicle shoppers to consider the total cost of the loan, not just the payment or advertised interest rate. Longer loan terms can reduce each payment while increasing the amount of interest paid overall.
Consider a simplified example.
Suppose you finance $20,000 for 60 months.
| Illustrative APR | Approx. Monthly Payment | Approx. Total Interest |
|---|---|---|
| 10.99% | $435 | $6,085 |
| 29.99% | $647 | $18,817 |
These figures are illustrative calculations only. They do not represent a Car Nation Canada financing offer and exclude applicable taxes, insurance, registration, optional products, lender fees, and other costs.
The difference demonstrates why vehicle selection becomes incredibly important when the interest rate is high.
At 29.99%, financing an extra $5,000 because a more expensive SUV looks appealing can be dramatically more costly than it would be for someone borrowing at a prime rate.
The dealership-insider approach is simple:
Buy enough vehicle for your needs without buying more vehicle than your rebuilding plan can comfortably support.
Start With the Used Car — Not the Maximum Approval
When rebuilding credit, the right car is usually the one that lets you succeed with the loan.
That could be a practical sedan for commuting, a compact SUV for a young family, a minivan for children and cargo, or a truck when your work genuinely requires one.
You can explore our current new and used vehicle inventory while keeping the financing decision separate from the emotional side of choosing a vehicle.
For example, a borrower commuting between Burlington and Hamilton may care more about fuel economy, reliability, insurance costs, and manageable kilometres than having every available luxury option.
Someone travelling throughout Grimsby, Niagara, or Brantford for work may need additional cargo room or highway comfort.
The question should be:
What vehicle lets me reliably live my life while keeping enough room in my budget to make every payment?
That is a much better starting point than asking how expensive a vehicle you can finance.
Watch Out for Long Terms and Negative Equity
A longer loan can make an expensive vehicle appear affordable because the balance is spread over more payments.
But stretching the loan does not make the vehicle cheaper.
The Financial Consumer Agency of Canada specifically warns that longer car loans generally increase the total amount of interest paid and can contribute to negative equity — the situation where you owe more on the loan than the vehicle is worth.
Negative equity matters even more when you are trying to rebuild credit.
Imagine making payments for two years and then deciding you want another vehicle. If your trade is worth $16,000 but you still owe $21,000, you have $5,000 of negative equity that must be dealt with.
Rolling that amount into another loan, when permitted, may leave you financing substantially more than your next vehicle is worth.
For a credit-rebuilding plan, stability is usually more valuable than frequently changing vehicles.
The 12-Month Credit-Rebuilding Game Plan
The first year after obtaining the loan deserves special attention.
The goal is not to obsess over your credit score every week. The goal is to establish predictable financial habits.
Month 1: Make the Payment Nearly Impossible to Miss
Set up automatic payments where available.
Then keep enough money in the account to prevent an NSF situation when the payment comes out.
Create a calendar reminder several days before each withdrawal so you can confirm the funds are available.
Months 2–3: Stabilize the Rest of Your Credit
A car payment does not exist in isolation.
Pay your credit cards, phone accounts, loans, and other obligations on time as well.
TransUnion recommends paying bills on time, monitoring balances, avoiding unnecessary new credit applications, and checking your report for inaccuracies as part of healthier credit management.
Months 4–6: Avoid the "My Score Improved, So I Can Borrow More" Trap
A small improvement does not mean it is time to open several credit cards or finance another major purchase.
The Government of Canada's credit guidance notes that numerous hard inquiries within a short period can affect your credit profile, while responsible payment behaviour can help strengthen it over time.
Keep the plan boring.
Boring is good.
Pay on time. Keep balances controlled. Avoid unnecessary applications.
Months 7–9: Check Your Credit Reports
Review the information being reported.
You can use TransUnion Canada's credit-improvement resources to learn more about checking your credit and disputing information you believe is inaccurate.
Also confirm that your vehicle loan is being reflected appropriately where applicable.
Before choosing a credit-building loan in the first place, it is reasonable to ask whether the lender reports repayment information to a credit bureau. TransUnion itself recommends asking prospective creditors whether they report account information.
Months 10–12: Prepare for a Financing Review
By this stage, you may have accumulated a full year of recent payment history.
That does not guarantee that your score has reached a particular number, nor does it guarantee access to a lower rate.
What it does give you is a sensible point at which to reassess your financial situation.
Review:
- Your current credit reports
- Current credit scores available to you
- Remaining auto-loan balance
- Current APR
- Number of payments remaining
- Any early repayment or loan-transfer conditions
- Your current income
- Changes in your other debts
Then determine whether investigating a lower-cost financing option is worthwhile.
Can You Refinance the Car Loan After 12 Months?
Potentially.
Refinancing generally means obtaining a new loan that pays out the old loan, leaving you with a different interest rate, term, payment, or combination of those factors.
You still need to qualify for that new financing.
The Government of Canada notes that transferring an existing loan to another financial institution may require obtaining a new loan and using it to pay the original one. Borrowers should also check for any applicable early-payment costs and compare the overall financial benefit.
Here is a simplified example of why a review can matter.
Suppose someone originally financed $20,000 over 60 months at 24.99%.
The approximate payment would be $587 per month.
After 12 regular payments, the remaining balance would be roughly $17,704.
If — purely as an illustration — that borrower subsequently qualified to refinance the remaining balance over 48 months at 12.99%, the approximate payment would fall to about $475 per month.
That is roughly $112 less each month.
Again, this is a mathematical example only. It is not an offer or prediction of what rate a borrower will qualify for after 12 months.
A lender will evaluate the application at that time.
A Lower Payment Is Not Automatically a Better Refinance
Here is another dealership-insider tip: do not judge refinancing exclusively by the payment.
If someone tells you they can cut your payment from $550 to $430, ask:
How?
If the answer is simply that the remaining debt has been stretched over several additional years, you may end up paying more interest rather than less.
Compare:
- APR
- Remaining balance
- New amount financed
- Loan length
- Payment
- Financing or administrative fees
- Total remaining cost of borrowing
The goal should be a genuinely stronger financial position, not just a smaller-looking payment.
What If You Have a Trade-In With Negative Equity?
Know the numbers before signing anything.
Find out approximately what your vehicle is worth and compare that amount with your current loan payout.
If the payout is higher, you have negative equity.
For example:
Loan payout: $22,000
Trade-in value: $18,000
Negative equity: $4,000
That $4,000 does not disappear.
Depending on lender approval and the transaction structure, it may need to be paid separately or become part of the financing discussion for the next vehicle.
Canada's consumer-finance guidance specifically recommends understanding negative equity and, where possible, avoiding trading while deeply underwater on an existing auto loan.
For someone rebuilding credit, keeping a reliable vehicle longer can sometimes support a cleaner financial recovery than repeatedly changing vehicles.
The Bigger Goal Is Not Just a Better Credit Score
A stronger score is useful, but it should not be the only target.
The bigger objective is to reach a point where:
- Bills are routinely paid on time
- High-interest debt is shrinking
- Credit-card balances are manageable
- Emergency savings are growing
- Transportation costs fit comfortably into the monthly budget
- You have more financing choices the next time you need credit
A vehicle loan should support that progress rather than consume every available dollar.
Conclusion: Treat the Car Loan as One Stage of the Comeback
Rebuilding credit with a used car is not about finding somebody willing to finance the most expensive vehicle possible.
It is about creating a manageable path forward.
Choose a dependable vehicle. Understand the APR and total borrowing cost. Keep the payment well within your real budget. Make every payment on time. Manage the rest of your credit carefully. Review your reports for errors. Then, after approximately a year of stronger financial habits, investigate whether a lower-cost refinancing option is available.
There are no guaranteed approvals, guaranteed credit-score increases, or guaranteed refinancing outcomes.
There are, however, financing options available for many credit situations.
If you are rebuilding after financial challenges, our team can help you explore an appropriate vehicle and financing structure without judgement. Start with the Car Nation Canada car-loan pre-approval process, then compare your budget against our current vehicle inventory.
O.A.C. — On Approved Credit. Conditions may apply.
Frequently Asked Questions
Can a used car loan help rebuild my credit?
Responsible management of a car loan may contribute to a stronger credit history when the lender reports the account and you consistently make payments as agreed. However, no loan can guarantee that your credit score will increase by a particular amount. Payment history is one factor credit-scoring systems may consider.
Can I get a car loan with a credit score between 300 and 559?
Financing options may be available for many credit situations, but approval is not guaranteed. Lenders consider more than the numerical score, including income, existing debt, the vehicle, loan amount, employment information, and overall credit history. All financing is O.A.C. Conditions may apply.
Is 29.99% a normal bad-credit car-loan rate?
There is no universal APR attached to a particular credit score. A figure such as 29.99% should be viewed only as an example of the high borrowing costs that may arise in some subprime financing situations. Your actual offer will depend on the lender and your complete application.
How long should I wait before trying to refinance?
There is no universal 12-month rule. A year of consistent payments can provide a logical time to review your progress, but refinancing depends on your current credit profile, income, remaining loan balance, vehicle, and available lenders. Compare the total remaining borrowing cost before replacing your existing loan.
What is the most important thing I can do while rebuilding credit?
Pay your obligations on time and avoid taking on more debt than you can comfortably handle. Both TransUnion Canada's credit guidance and Canadian federal consumer guidance identify responsible, punctual payment behaviour as an important part of maintaining or improving credit health.