
How to Apply for an Auto Loan in Ontario: Step-by-Step Guide
How to Apply for an Auto Loan in Ontario: Step-by-Step Guide
Posted on September 16, 2026
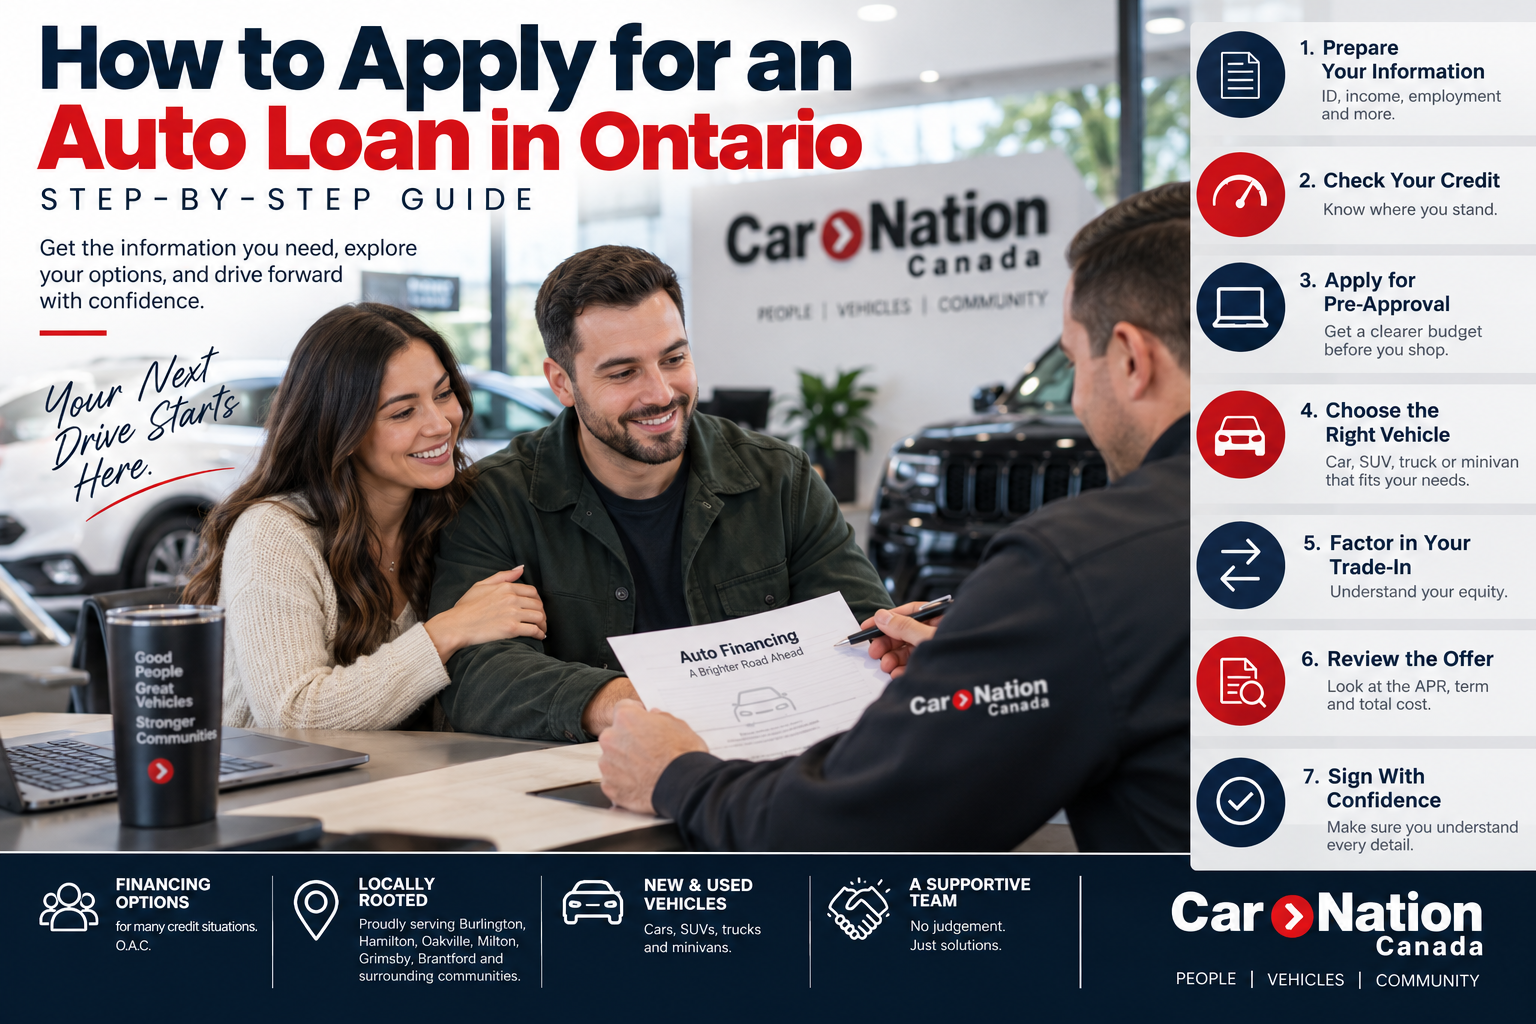
How to Apply for an Auto Loan in Ontario: Step-by-Step Guide
Learn how to apply for an auto loan in Ontario, what information you may need, how pre-approval works, and what to review before financing your next vehicle.
Applying for an auto loan can feel complicated, especially if you are buying your first vehicle, rebuilding your credit, managing a tighter family budget, or establishing credit as a newcomer to Canada.
The good news is that understanding how to apply for an auto loan becomes much easier when you break the process into steps. At Car Nation Canada, our goal is to help you understand your options, find a vehicle that works with your budget, and make an informed financing decision without judgement or unnecessary pressure.
Whether you are shopping in Burlington, Hamilton, Oakville, Milton, Grimsby, Brantford or elsewhere in Southern Ontario, the basic auto loan application process is similar.
Key Takeaways
- Start with a realistic vehicle and monthly budget before applying.
- Auto loan applications commonly ask for identification, address, employment, income and housing information.
- Your credit history can affect your financing options and interest rate, but financing options are available for many credit situations.
- Pre-approval can help you understand your potential budget before choosing a car, SUV, truck or minivan.
- Compare more than the payment. Look at the APR, loan term, amount financed and total cost of borrowing.
- Be completely accurate when completing a credit application.
- If you have a trade-in, find out whether there is positive equity or negative equity before finalizing the deal.
- All financing is O.A.C. — On Approved Credit. Conditions may apply.
How Do You Apply for an Auto Loan?
An auto loan allows you to borrow money to purchase a vehicle and repay that amount over an agreed loan term.
Instead of paying the entire purchase price upfront, you make scheduled payments that generally include principal and interest.
The exact financing terms available to you can depend on factors such as your credit history, income, existing debt obligations, the amount being financed, the vehicle and the lender's requirements.
In Canada, lenders use information in your credit report and credit score when deciding whether to offer credit and what interest rate may apply. The Financial Consumer Agency of Canada notes that lenders may use your credit history when deciding whether to lend money and how much interest to charge.
Here is how the process generally works.
Step 1: Decide What You Can Comfortably Afford
Before filling out an auto loan application, start with your budget.
It can be tempting to ask, "What vehicle can I get approved for?" A better starting point is often, "What vehicle payment fits comfortably into my budget?"
Consider more than the loan payment.
Your vehicle budget may need to account for:
- monthly or bi-weekly loan payments
- insurance
- fuel
- maintenance
- tires
- parking
- registration and licensing
- unexpected repairs
- other household expenses
A payment-focused commuter may have very different priorities from a growing family looking for an SUV or minivan.
Likewise, someone replacing a work truck may need to balance purchase cost with reliability, capability and expected kilometres driven.
You can begin by exploring Car Nation Canada's new and used vehicle inventory to compare cars, SUVs, minivans and trucks at different price points.
Step 2: Gather the Information for Your Auto Loan Application
Having your information ready can make the application process easier.
The exact documentation required depends on the lender and your circumstances, but an auto loan application may ask for information such as:
- full legal name
- date of birth
- current address
- previous address if you recently moved
- phone number and email address
- employment information
- job title
- length of employment
- income information
- housing status
- monthly rent or mortgage payment
- vehicle of interest
- approximate monthly budget
Additional documentation may sometimes be requested to verify the information supplied in the application.
Car Nation Canada's online car loan pre-approval application asks for information including your estimated credit score, monthly budget, address, housing costs, employer, job title and gross monthly income before an application is submitted for consideration.
The most important rule is simple: be accurate.
OMVIC advises consumers to carefully verify the information entered on a dealership credit application. Inflating income or minimizing debts in an effort to obtain an approval is not appropriate, and consumers should review application information before authorizing its submission.
Step 3: Check Your Credit Before Applying for an Auto Loan
You do not necessarily need perfect credit to explore vehicle financing.
However, understanding your credit situation before applying can help you know what lenders may see.
Canada has two main credit bureaus: Equifax and TransUnion. According to the Financial Consumer Agency of Canada, Canadians can access their credit reports online for free through both bureaus, and checking your own credit report or score does not affect your credit rating.
Review your report for:
- accounts you recognize
- correct balances
- payment history
- incorrect personal information
- accounts that should be closed
- potential signs of identity theft
- other errors
If something is incorrect, you have the right to dispute information you believe is wrong. The Government of Canada recommends checking reports from both Equifax and TransUnion because the information may not always be identical.
Knowing where you stand can also make conversations about auto financing more productive.
Step 4: Apply for Auto Loan Pre-Approval
One of the easiest ways to begin is to request pre-approval before committing to a particular vehicle.
A car loan pre-approval is a preliminary financing decision based on the financial and credit information available to the lender.
It can give you a clearer idea of the type of financing that may be available and help narrow your vehicle search to options that make sense for your budget.
At Car Nation Canada, you can apply for auto financing online before or while shopping for a vehicle.
A pre-approval should not be confused with guaranteed financing. Final approval may depend on lender requirements, verification of the information supplied, the vehicle selected and other conditions.
Financing options are available for many credit situations. O.A.C. — On Approved Credit. Conditions may apply.
Step 5: Choose a Car, SUV, Truck or Minivan That Fits the Budget
Once you have a better idea of your financing range, you can focus on finding the right vehicle.
This is where shopping by total budget, rather than just monthly payment, becomes especially important.
For example, a commuter travelling between Burlington and Hamilton may prioritize fuel efficiency and reliability in a sedan or compact SUV.
A family in Oakville or Milton may need additional passenger and cargo space from an SUV or minivan.
Someone driving throughout Grimsby, Niagara or Brantford for work may prefer the capability of a truck.
Car Nation Canada provides access to both new and pre-owned options. You can browse available vehicles here and compare vehicles that fit your needs before finalizing financing.
Step 6: Include Your Trade-In, If You Have One
If you currently own a vehicle, your trade-in may affect how much you need to finance.
There are two basic situations.
Positive Equity
Positive equity means your vehicle is worth more than the amount you still owe on its loan.
That difference may be available to apply toward your next vehicle purchase.
Negative Equity
Negative equity means you owe more on your existing vehicle loan than the vehicle is currently worth.
For example, if your loan payout were $25,000 and the vehicle were valued at $20,000, there would be $5,000 in negative equity.
How that amount is handled can affect the financing required for your next vehicle.
This is why knowing your current loan payout and obtaining a realistic trade-in value are important before completing your next purchase.
OMVIC specifically recommends that vehicle buyers consider whether a new purchase may create or involve negative equity when reviewing financing.
Step 7: Review the Auto Loan Offer Carefully
Getting approved is not the end of the decision-making process.
Before signing, understand exactly what you are agreeing to.
Important numbers to review include:
- vehicle selling price
- down payment, if applicable
- trade-in value
- outstanding trade-in loan balance
- amount financed
- annual percentage rate or APR
- payment amount
- payment frequency
- loan term
- cost of borrowing
- total amount of required payments
- optional products you have chosen
Ontario financing agreements have disclosure requirements designed to give consumers a clearer picture of the transaction. OMVIC notes that finance arrangements include information such as APR, payments, term, cost of borrowing, total required payments and the vehicle's cash price.
Do not focus solely on getting the lowest possible monthly payment.
A longer term can reduce the size of each payment while potentially keeping you in debt longer. What matters is finding a balance between a manageable payment, appropriate loan term and overall borrowing cost.
Step 8: Read the Contract Before Signing
Take the time to review your contract.
Check that the numbers match what was discussed and that you understand any optional products or services included in the transaction.
OMVIC advises consumers to verify that the rate and financing terms shown on the final contract match what they were promised. It also recommends getting important verbal promises in writing.
Ask questions if anything is unclear.
A financing decision should make sense to you before you sign it.
Can You Apply for an Auto Loan With Bad Credit?
Yes, you can apply for auto financing even if your credit history has had challenges.
Approval is never automatic, but lenders may consider applicants with a range of credit profiles.
That may include people who have experienced:
- missed payments
- collections
- high credit utilization
- limited credit history
- a previous consumer proposal
- a previous bankruptcy
- recent changes in employment or income
- other financial setbacks
Your credit history is one factor lenders may consider alongside income, current obligations, vehicle choice and other underwriting requirements.
For someone rebuilding financially, the objective may be different from a prime-credit shopper. Rather than stretching for the most expensive vehicle available, it may make more sense to find reliable transportation with payments that leave room in the household budget.
Our team works with shoppers in different financial situations without judgement. You can start with Car Nation Canada's online financing application to explore available options.
O.A.C. Conditions may apply.
Can Newcomers to Canada Apply for an Auto Loan?
A newcomer may have stable employment and income but still have a thin Canadian credit file.
That does not necessarily mean there are no financing options.
Lenders may have different policies regarding limited credit history, income verification and documentation, so applications are evaluated individually.
If you recently moved to communities such as Burlington, Hamilton, Oakville, Milton or elsewhere in Southern Ontario, our team can help explain the application process and what information may be needed.
The goal should be to find a financing structure and vehicle that align with your actual budget rather than simply focusing on the maximum amount potentially available.
Does Applying for an Auto Loan Affect Your Credit?
When a lender reviews an application for new credit, a credit inquiry may be recorded on your credit report.
The Financial Consumer Agency of Canada identifies how often you apply for new credit as one of the factors that can affect a credit score.
OMVIC also advises car buyers to understand where their application is being submitted when a dealership works with lenders.
By contrast, requesting your own credit report from Canada's main credit bureaus does not affect your credit rating.
What Matters Most When Comparing Auto Loans?
Monthly payment matters, but it is only part of the picture.
Suppose two financing offers both appear affordable each month.
One may have a shorter term and lower overall borrowing cost, while another may extend repayment for considerably longer.
Before deciding, ask:
- What is the APR?
- What is the loan term?
- How much am I actually financing?
- What is my cost of borrowing?
- What will I pay in total?
- Does the payment comfortably fit my budget?
- Is there negative equity in my trade?
- Are there optional products included?
- Do I understand every number on the contract?
That broader view helps you make a financing decision based on your financial situation instead of one attractive payment figure.
Ready to Apply for an Auto Loan in Ontario?
Learning how to apply for an auto loan is largely about being prepared.
Know your budget, gather accurate information, review your credit, explore pre-approval, choose a vehicle that fits your needs and carefully review the financing terms before signing.
Whether you are rebuilding your credit, purchasing your first vehicle, looking for reliable transportation for your family or establishing yourself as a newcomer to Canada, you do not have to figure everything out alone.
Car Nation Canada's team serves drivers throughout Burlington, Hamilton, Halton, Oakville, Milton, Grimsby, Brantford and surrounding Southern Ontario communities.
Start by applying for financing with Car Nation Canada, then browse our new and used vehicle inventory to find a car, SUV, truck or minivan that works for your needs and budget.
Financing options are available for many credit situations. O.A.C. — On Approved Credit. Conditions may apply.
Frequently Asked Questions About Applying for an Auto Loan
What do I need to apply for an auto loan?
You will generally need to provide personal, contact, housing, employment and income information. Depending on the lender and your situation, additional documentation may be requested to verify the application.
Can I apply for a car loan before choosing a vehicle?
Yes. A pre-approval application can help establish a potential financing range before you choose a specific vehicle. Final approval may still depend on the vehicle selected and lender requirements.
Can I apply for an auto loan if I have bad credit?
You can apply. Financing options are available for many credit situations, but approval, interest rate and terms depend on the lender's assessment of your application. O.A.C. Conditions may apply.
Should I make a down payment on a financed vehicle?
A down payment can reduce the amount that needs to be financed, but the amount that makes sense depends on your savings, budget, vehicle and financing terms. Some financing arrangements may not require a down payment, subject to approval and conditions.
Is the lowest monthly payment always the best auto loan?
Not necessarily. Compare the APR, loan term, amount financed, cost of borrowing and total required payments alongside the payment amount. A lower payment achieved by extending the loan considerably may result in a different overall borrowing cost.